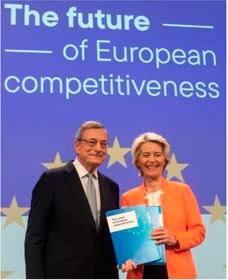
Former ECB President and Italian PM Mario Draghi with President of the European Commission Ursula von der Leyen launching the Draghi report in September 2024.
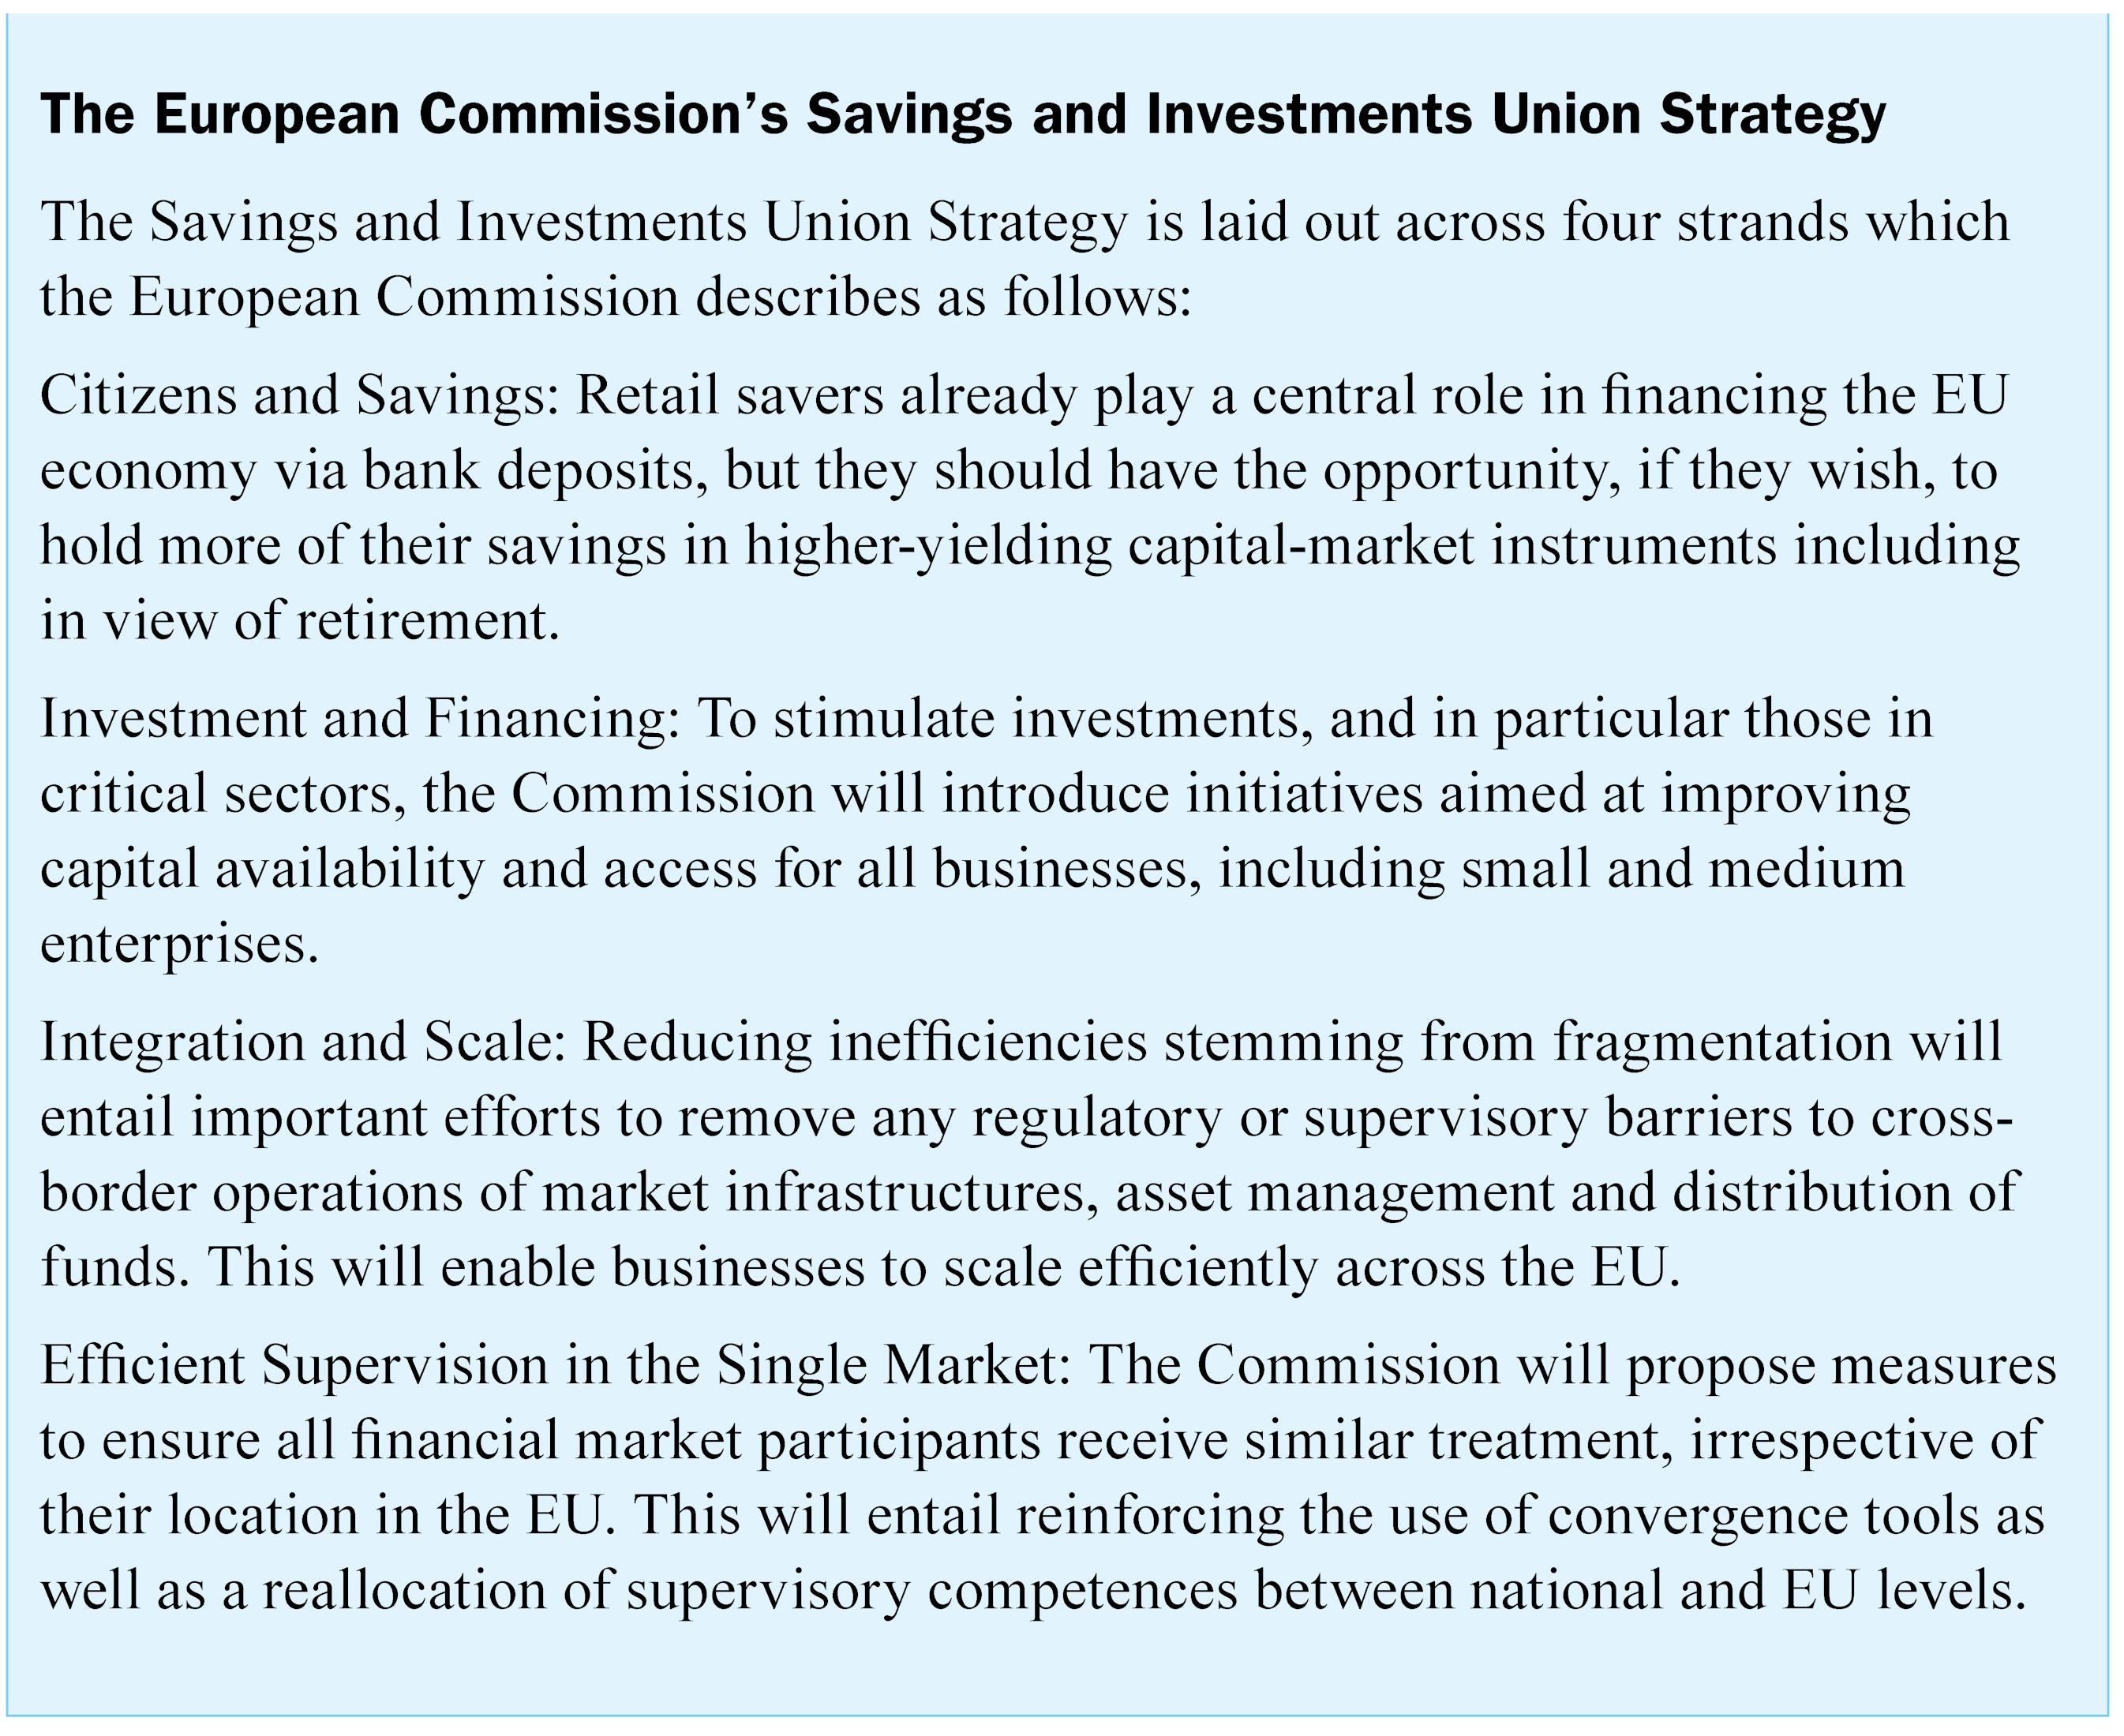
The rebranding and relaunch of the Capital Markets Union (CMU) project, as the ‘Savings & Investment Union’ is intended to give renewed momentum to a project which predates the UK’s vote to leave the EU, and which was intended to mirror in success terms that other great financial achievement of the EU - the creation of the single currency, the euro, now in its 26th year. The rebranding as SIU is intended to help give momentum by depicting for people more simply what a single market for capital will mean for EU residents and corporates – greater choice, opportunities and avenues to save, invest and access capital – although getting to that stage will not be a straightforward process.
Any progress on SIU at an EU level will likely be additive to efforts in Ireland to implement findings in the Funds Sector 2030 report to encourage greater retail investor participation as well as the delayed, but well-advanced, efforts to increase pension coverage through auto-enrolment.
The European Commission’s earlier efforts for CMU/SIU lost momentum when, in the immediate aftermath of the Brexit vote, then UK Commissioner Lord Hill, who had been spearheading the project that would have most likely elevated London’s role in global capital markets to an even greater level, resigned from his role, in part to avoid ‘a very bad start’ to Brexit negotiations as he told a Finance Dublin Conference in 2017.
In 2014, Lord Hill’s stated timeline for EU CMU was 2019 with the urgency to make progress on the topic reduced as a result of intense Brexit negotiations and the impact of the COVID 19 pandemic. The most recent renewed efforts to progress EU capital markets integration has been driven by two separate reports – the Letta report (that focuses on the future of the Single Market), published in April 2024, and the Draghi Report (which focuses on addressing European competitiveness and the future of the European Union) published in September 2024.
These efforts are now led by former Portugal Minister for Finance Maria Luis Albuquerque, the new European Commissioner for Financial Services and the Savings and Investments Union, with Ireland set to play a major role as the project will likely be a priority under Ireland’s Presidency of the Council of the European Union in the second half of 2026.
Banking and Payments Federation Ireland
Banking and Payments Federation Ireland, in its response to the Commission consultation, states its fully supports ‘the EU’s ambition to build deeper, more liquid, and globally competitive capital markets’ and to realise this goal says the ‘EU must foster a stronger investment culture underpinned by pragmatic, risk-based supervision. Regulation - when well designed - can drive market resilience, spur innovation, and deliver better outcomes for end investors.’
BPFI’s recommendations for the Commission to help integrate the EU’s capital markets include ensuring proportionality of regulation for firms, standardising post-trade infrastructure, harmonising regulatory requirements & supervisory outcomes, reducing the cost of market data and strengthening best execution rules.
On proportionality the BPFI says the EU regulatory framework should be better tailored to the actual risk profile of different firms (and recommends the creation of a standalone framework for investment firms). Such a proportional application of regulation ‘would support the international competitiveness and attractiveness of EU markets’ and BPFI recommends that the idea of international competitiveness should be ‘an explicit objective in all EU financial-markets regulations’ and that a competition and competitiveness mandate should be enshrined in the three European supervisory agencies - the EBA, EIOPA and ESMA. Tailored rules that align to firms’ business models and risk profiles would remove overlapping rules and guidance, it says.
To help align regulatory requirements and supervisory outcomes BPFI says that EU legislation should be in the form of regulations, rather than Directives, where possible.
Currently, national competent authorities (the Irish NCA in financial services is The Central Bank of Ireland) transpose, implement and interpret Directive provisions differently, resulting in patchwork practices across the EU. BPFI, in its response writes, ‘a Regulation would bind all NCAs to the same text and remove discretion in transposition, fostering genuine supervisory convergence.’ Legislating at the EU level with regulations as opposed to directives would also prevent national level ‘gold-plating’, which fragment the single market, ensuring consistent application across Member States. This would help to prevent duplicative national laws and would have the positive knock-on effect of helping to reduce compliance costs.
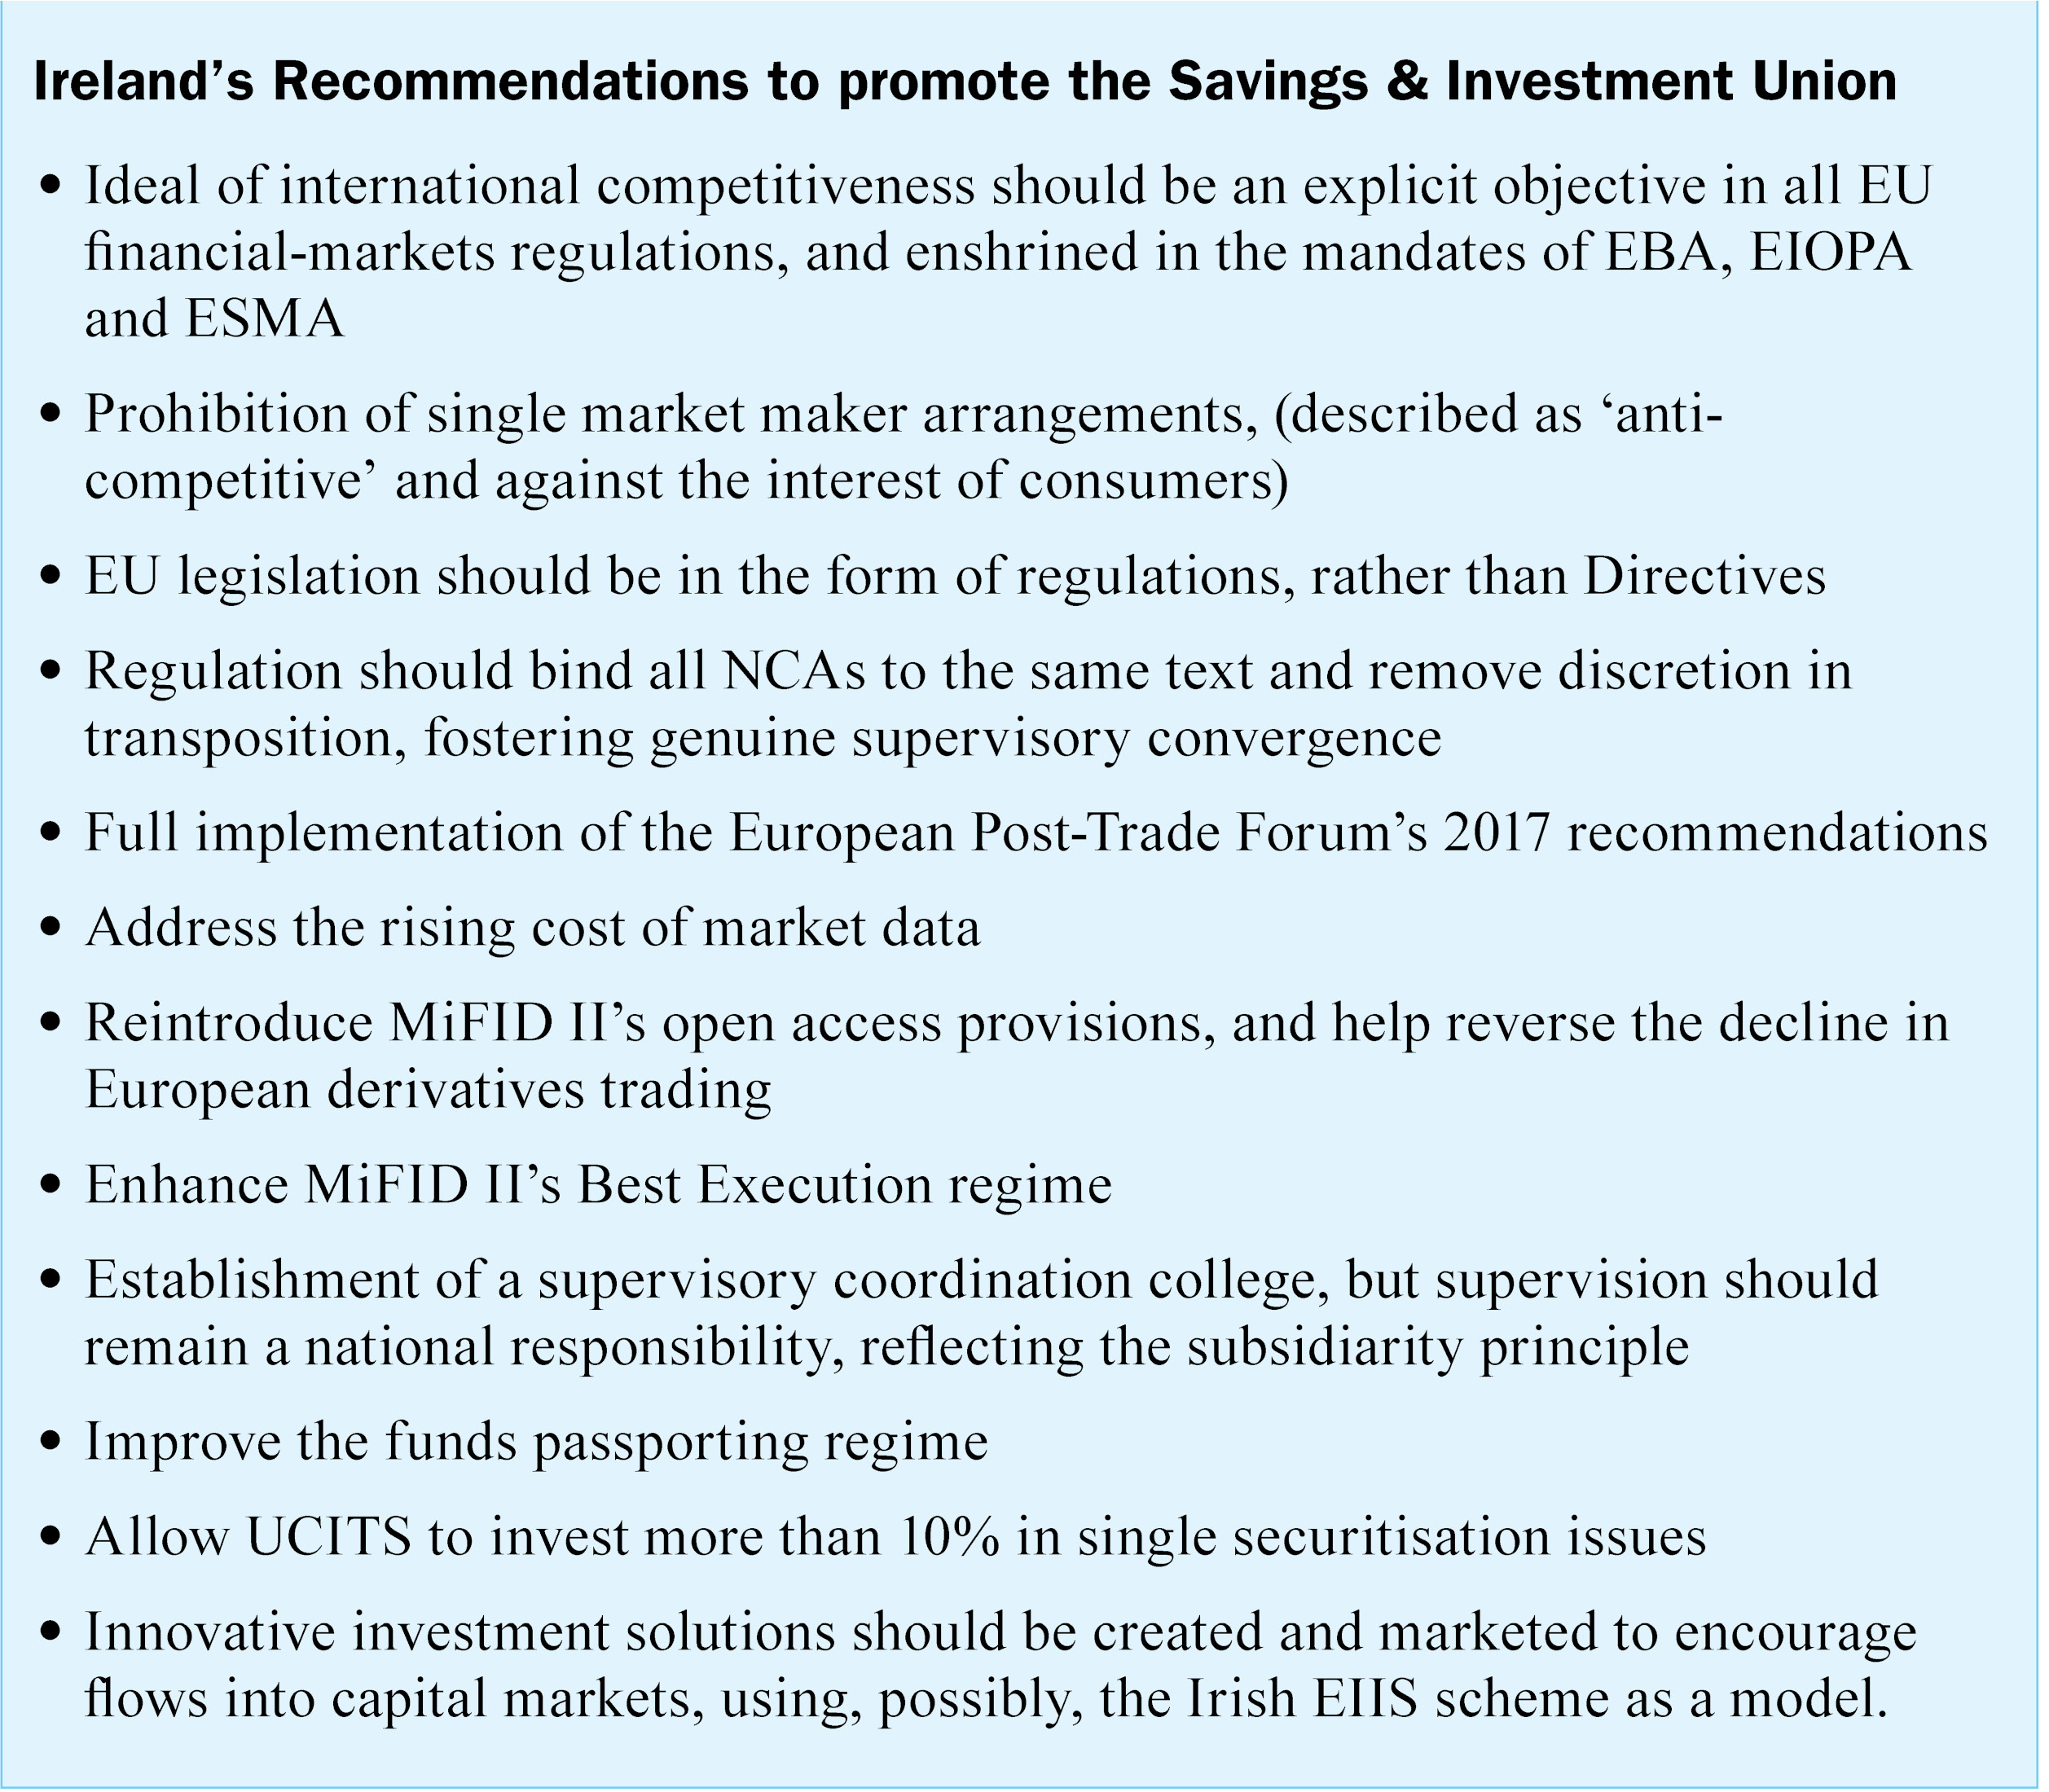
BPFI also calls for changes in post-trade infrastructure to integrate capital markets across the EU. ‘The EU must focus on standardising post-trade processes in order to reduce costs, increase efficiency, and support true cross-border activity. As part of this, it is crucial that barriers to settlement interoperability are removed and that policymakers look to fully implement the European Post-Trade Forum’s 2017 recommendations.’ It describes the EU’s securities‐settlement landscape as ‘highly fragmented’ due to ‘siloed’ Central Securities Depositories (CSDs), manual processes and local requirements while ‘domestic registration, divergent insolvency regimes and gold-plated national laws prevent interoperability’ and combine to drive up costs. It says the European Post-Trade Forum’s recommendations would ‘streamline processes, cut counterparty and systemic risk, and enable genuine cross-border consolidation of CSDs.’ It also holds up post-Brexit Ireland as an example of how a more consolidated post-trade environment in the EU could work, drawing attention to Ireland’s willingness to accept not having its own national CSD and fully complying with the law and requirements of another Member State, namely Belgium.
Amongst the BPFI’s comprehensive submission on SIU it also makes a number of more focussed recommendations to improve market efficiencies, increase competition and lower costs.
Amongst the recommendations it makes is the prohibition of single market maker arrangements, which they describe as ‘anti-competitive and have no real benefit for retail customers...we believe that retail customers do not always receive the best price given the lack of competition.’ It adds, ‘We believe the EU needs to take a firm position and prohibit the use of single market maker arrangements that are permitted in certain EU Member States...Real price competition can only emerge when multiple market makers are permitted to compete openly.’
BPFI also calls for the rising cost of market data to be addressed. ‘Rising costs and opaque pricing of market data pose real barriers to entry and only serve to make EU markets less attractive. The costs of market data must be improved to support competition and enable participation across the market.’ It also recommends the reinstatement of open access for listed derivatives, ‘The recent removal of MiFID II’s open access provisions was a missed opportunity. Reintroducing these rules would promote choice, reduce systemic risk, and help reverse the decline in European derivatives trading.’
On ‘best execution’ BPFI recommends that the EU should avoid adopting a US-style Order Protection Rule and instead enhance MiFID II’s Best Execution regime, ‘We believe this will better preserve market quality while avoiding unnecessary complexity’, it says in its submission.
Irish Funds
Irish Funds, in its response to the Commission’s SIU consultation, said while it fully supports the overarching objectives to deepen capital markets integration, harmonise supervisory practices, and reduce fragmentation across the Union, ‘it is essential that any proposed reforms are proportionate, evidence-based, and grounded in the operational realities of the funds and asset management sector.’
The funds industry representative body outlines a number of its key positions that would enhance the investment and asset management sectors’ ability to contribute fully to SIU including greater proportionality in the regulatory framework, alignment of supervisory outcomes and regulatory harmonisation, including the establishment of a supervisory coordination college, and calls for National Competent Authorities to retain supervisory responsibility for the sector. In addition it sees no need at this time to reopen key investment fund-related directives such as AIFMD and UCITS.
On the regulatory framework Irish Funds ‘agrees there is a need for greater proportionality in the EU regulatory framework for trade, post-trade, asset management, and funds sectors. We advocate for proportionality in the design and application of EU legislative and regulatory frameworks, tailoring regulation to risk rather than adopting a ‘one-size-fits-all’ approach.’
It adds that ‘alignment of supervisory outcomes is what is key to delivering a stronger integrated market and this is not dependent on new direct supervisory mandates and governance models, especially in the short term’.
It says ‘market integration is best supported through regulatory harmonisation, supervisory convergence, and strong cross-border cooperation between NCAs. While ESMA plays a valuable role in fostering supervisory convergence, asset management supervision should remain a national responsibility, reflecting the subsidiarity principle and the complexity of local market environments. As a result, Irish Funds supports retaining the current supervisory model in which NCAs maintain supervisory responsibility, while convergence is promoted through better use of existing structured cooperation tools such as peer reviews, common methodologies, and cross-border information sharing. Irish Funds would also support a supervisory coordination college comprised of all relevant NCAs and ESMA while supervisory responsibilities remain unchanged. ‘We believe this model, where colleges exist for information-sharing and informal coordination, supports supervisory convergence without interfering with primary supervision.’
Irish Funds adds that while regulatory convergence is welcome it warns that ‘regulatory and supervisory convergence should not be pursued as an end in itself. While it is crucial to ensure comparability and a level playing field, existing divergences across member states should not be systematically perceived as unfavourable. In many cases, divergence occurs either to take into account, within a common framework, national specificities or to specify and accommodate general EU law requirements to concrete firm/market operational requirements.’
On the EU directives that have shaped the EU’s funds industry, notably AIFMD and UCITS, Irish Funds is against reopening what are cornerstones of Ireland and the EU’s investment funds industry to support stability and legal certainty for the sector. ‘AIFMD has just undergone a comprehensive review with targeted updates, which should be implemented and evaluated before further legislative change. The UCITS framework is seen as a cornerstone of EU retail investor protection and a successful cross-border regime, and reopening it risks undermining its stability and global reputation. Instead, we suggest the focus should be on effective implementation, supervisory convergence, and consistent application of existing rules. This would provide legal certainty and support integrated capital markets.’
Away from supervisory framework issues Irish Funds says it is supportive of development of DLT/blockchain and tokenisation to enhance asset mobility and accessibility via integrated platforms and says the authorisation process for AIFMD and UCITS is ‘generally clear and comprehensive’ but advises enhancements could be made through the use of ‘standardised electronic forms and clearer application of the proportionality principle’.
It sees space for improvement in the funds passporting regime which it says is not sufficiently simple and proportionate and suggest’ they could be simplified to a notification process for EU domiciled funds. Irish Funds also supports extending increased investment limits beyond index replication strategies, as well as allowing UCITS to invest more than 10% in single securitisation issues, changes it says could be made through Level 2 or Level 3 amendments.
Insurance Ireland
In responding to the European Commission’s call for evidence on SIU, Insurance Ireland said the insurance industry can be a key contributor and enabler to achieving the SIU objectives.
While cautioning that it is critical for consumers to be fully aware of the high risks that investing in capital markets entails, Insurance Ireland says the insurance industry can support retail investors’ participation in the capital markets through a number of avenues, including marketing and awareness, ‘The industry could raise awareness through informative content, advertising/consumer education campaigns, webinars, etc. highlighting the benefits of participation in capital markets for the individual customer and the wider society,’ adding that these efforts would benefit greatly if there was a level playing field in terms of tax treatment.
It also sees product innovation as another opportunity for the insurance industry to back the Commissions’ SIU goal ‘through the range of pension, saving and investment products offered by the insurance sector, innovative investment solutions could be created to encourage flows into capital markets.’
The third main area it highlights in its submission is the provision of high-quality advice to consumers. ‘The insurance industry can provide financial advice which would be crucial for customers considering investments. While increased participation in capital markets can offer higher returns, it can also come with higher risks. Educating clients about the potential volatility and ensuring they understand the risks associated with different investment products will be essential.’ It adds that advances in technology allow the industry to tailor client and engagement on a case-by-case and investment-by-investment basis. ‘This could range from robo-advice for straight forward, monthly savings, which could free up advisers to provide higher value-added, comprehensive advice at key inflection points...’
It adds that ‘the rationalisation and streamlining of regulations and disclosure requirements would facilitate the creation of more meaningful interactions and communications with customers where the core messages could be put front and centre, making it easier for consumers to engage with the industry.’
Looking at what domestic Irish measures could be implemented to support the EU-wide goals of SIU, Insurance Ireland highlighted a number of areas in which it is actively engaged with the Government – these include removal of 1% levy on life assurance policies; the equalization of the life assurance exit tax (LAET) rate (currently at 41%) with Deposit Interest Retention Tax (DIRT)/Capital Gains Tax (CGT) rates (both currently at 33%); the removal of 8-year deemed disposal requirement; and tax relief on losses in equivalent investments – all recommendations that also made it into the Department of Finance’s Funds Sector 2030 report.
It also highlights the potential in introducing a tax-efficient savings account, ‘the UK Individual Savings Accounts (ISA)-style allowances could attract huge investments from deposit accounts. These allowances could be restricted so that they are only available if the investment is aligned to “achieving wider economic and social objectives, notably supporting the green and digital transitions and ensuring economic and social sustainability for the EU in the long term’.
It adds that ‘there is a need for tax incentives for retail investors to invest in start-ups and young innovative companies, as well as tax incentives for these companies and even companies which are established but which are not publicly listed, in order to make it attractive for them to take investment from retail investors. The Irish Employment Investment Incentive Scheme (EIIS) is a potential model which could be viewed as a starting point. This type of scheme employed at a Europe-wide level, in order to increase the pool of appropriate investment opportunities, as well as increasing the pool of retail investment assets, could go some way to achieving the desired outcomes.’
On the topic of leveraging retail investors for start-up funding Insurance Ireland writes, ‘The challenge with identifying appropriate investments at an Irish scale can be seen with the recent broadening of rules for EIIS in order to open up the scheme to a wider range of companies. Limited liquidity and long lock-in periods which would be typical of private placements may also be an issue for a material proportion of retail investors...from an attitude to risk perspective, the vast majority of retail investors fall into a medium risk category (3 and 4 on a 7-point scale). The types of investments mentioned, such as in start-ups are likely to be high or very high risk, so a key challenge will be to create investment opportunities which match consumers attitude to risk.’
It adds that while the Commission is trying to see how these type of investments (retail investment in innovative/start-up companies) can be encouraged and facilitated ‘providers and regulators should be mindful that in other areas, such as the IORPS II Directive, there has been a move to curtail/discourage investment in unregulated markets. While these rules do not fully prohibit investment, it is likely to create an impression with consumers that investments in unregulated markets are riskier and should be avoided. Taking all of these into consideration, the focus should be on incorporating investments into young, innovative companies as a minority allocation in the retail investor’s overall portfolio.’
In addition to the start-ups, Insurance Ireland also sees potential, through appropriate vehicles, in encouraging retail investment in alternative investments such as critical infrastructure, affordable housing and the green transition.
To foster a broader European retail investor base Insurance Ireland calls for an end-to-end review of current regulation and disclosure requirements to be carried out at domestic level to assess how domestic and European requirements interact. ‘From the retail consumers perspective, there is a large volume of mandatory information provided to them, in addition to the core information from the product provider and advisor where relevant, which creates complexity and confusion for the consumer. This complexity should be addressed both domestically and at EU level.’
Insurance Ireland also gives detailed insight into the Commission’s plans to develop a pan-European simple and low-cost investment product. It writes ‘the creation of a simple and low-cost saving and investment product at European level might look sensible, however, we note that simple and low-cost savings and investments products are already available in the Irish and other Member States’ markets’ adding that its introduction ‘could cause additional complexity and duplication in the marketplace and confusion for consumers.’
Diversity of markets is retained therefore in its concept, illustrating the point, reflected also in in the contributions of the other bodies referenced here that the principles of subsidiarity, and collegiality, in the shared sovereignty pool of regulation and supervision that characterises the evolving European regulatory model is one to be preserved while seeking the gains from trade of the great vision of capital markets union that are potentially there for Europe to seize.