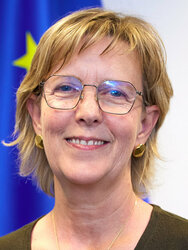
Maria Luis Albuquerque
The proposals aim to reduce costs for issuers and investors in EU securitisations and simplify due diligence and transparency requirements. Amendments to the Capital Requirements Regulation (CRR), the Liquidity Coverage Ratio (LCR) and Solvency II are also proposed as part of the package to boost the use of securitisation. The Commission’s move to update the EU’s securitisation framework follows recommendations to do so in both the Draghi and Letta reports.
The Commission sees the relaunch of European securitisation helping increase the amount of financing available to the real economy and says a well-functioning securitisation markets can contribute to higher economic growth and facilitate funding of Union strategic objectives, including investments in the green, digital and social transition. This is done by enabling banks to effectively and efficiently transfer risks to those that are best suited to bear them (ie. investors) and thereby free up their capital for further lending into the real economy. It is hoped that banks will use this freed-up capital for additional lending to households and businesses, including SMEs. Fitting in with the broader SIU strategy, securitisation can also provide capital market investors with more investment opportunities.
The EU securitisation framework was put in place in the aftermath of the 2008 financial crisis in response to concerns about risky US securitisations. At the time, strict requirements were seen as necessary to restore the reputation of the securitisation market and the EU’s current securitisation framework, which includes the EU’s STS securitisation standard, has been in place since 2019.
The latest proposals aim to find a better balance between safeguards and growth opportunities by reducing undue operational costs for issuers and investors, balancing with adequate standards of transparency, investor protection and supervision and by adjusting the prudential framework for banks and insurers by lowering capital requirements, to better account for actual risks and remove undue prudential costs when issuing and investing in securitisations. In addition, an enhanced role for the European Supervisory Agencies, especially the EBA, is envisaged.
European Commissioner for Financial Services and the Savings and Investments Union Maria Lu?s Albuquerque commenting on the proposals said they ‘will contribute to reviving the EU securitisation market by simplifying and enhancing our regulatory and prudential framework while preserving robust safeguards to ensure financial stability. This review can contribute to deepening our capital markets and financing the EU’s strategic priorities, in line with the Savings and Investments Union objectives. However, a vibrant securitisation ecosystem cannot be achieved by regulation alone and is not an end in itself. We count on the support of the financial industry to strengthen the EU securitisation market and I clearly expect it to use this fit-for-purpose framework to provide more funding to households and business, including SMEs.’
Ireland continues to attract securitisation activity with law firm Matheson recently advising Ferovinum, a UK-based fintech firm that acts as a funding and supply chain platform for drinks businesses, in the first ever asset-backed securitisation of wine and spirits receivables. The novel securitisation is a $550m asset backed securitisation program backed by Pollen Street Capital and a leading investment bank. The deal allows Ferovinum to expand its existing UK service offerings to businesses in the United States and European Union, as well as Australia later this year.